How to Navigate Rising Mortgage Rates: Strategies for First-Time Homebuyers in Today’s Market
Introduction
Homeownership is a dream for many first-time buyers, but rising mortgage rates can make the process seem more daunting than exciting. In today’s market conditions, where interest rates are higher than they’ve been in years, it’s critical to approach the home-buying process with a strategic plan. Luckily, there are effective ways to navigate these challenges while still securing your dream home. Let’s break it down.
Understanding Rising Mortgage Rates
The mortgage rate environment has shifted significantly over the last couple of years. For much of the past decade, historically low interest rates made buying a home more affordable. However, due to economic uncertainties and higher inflation, mortgage rates have steadily increased. In 2023, we’ve seen rates hover in the 6-8% range for a 30-year fixed-rate loan—up from about 3% just a few years ago.
So, what does this mean for first-time homebuyers? It means borrowing money to purchase a home is more expensive, leading to higher monthly payments. But don’t worry—there are steps you can take to minimize the impact of higher rates and still move forward with confidence.
Strategies for First-Time Homebuyers: Managing Higher Rates
1. Boost Your Credit Score
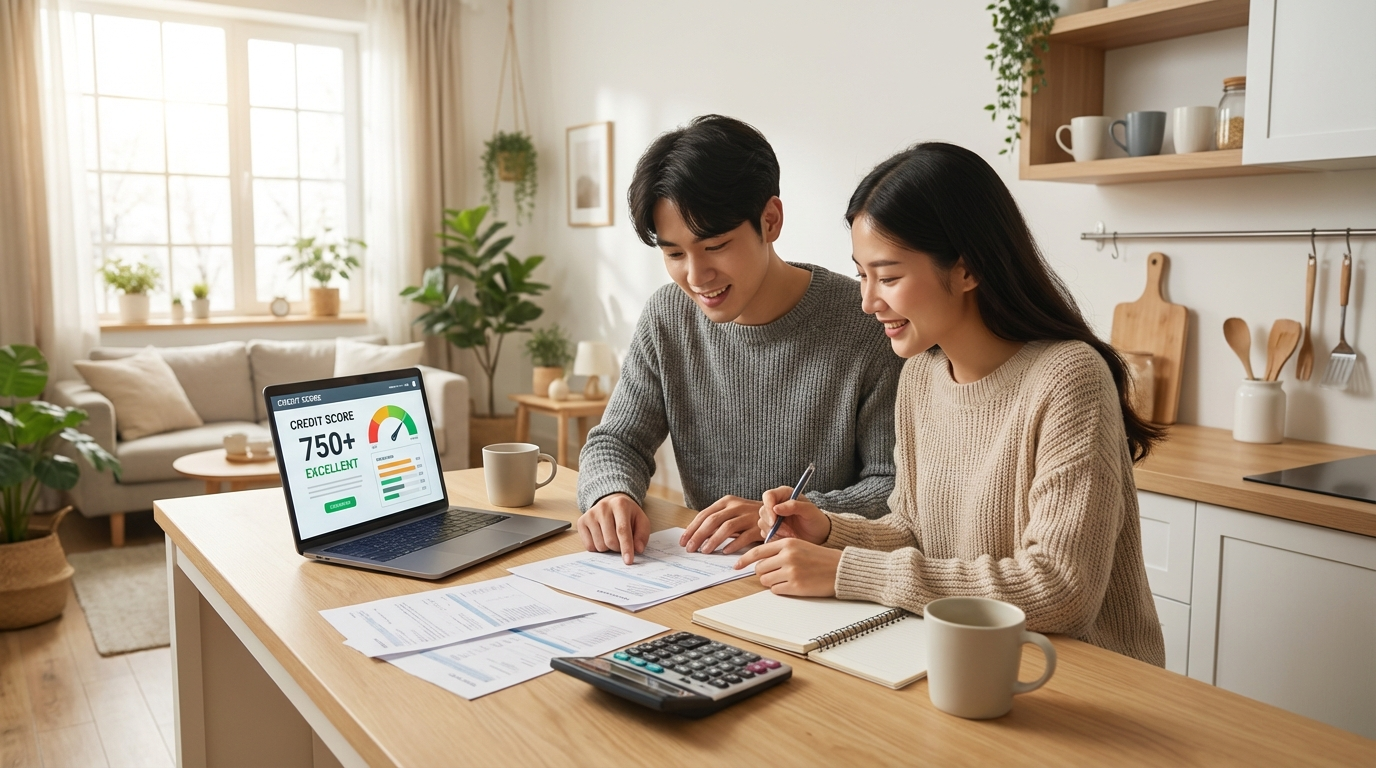
Your credit score plays a significant role in determining the interest rate you’ll receive from lenders. The higher your score, the lower your rate is likely to be. Here are a few tips to improve your credit profile before applying for a mortgage:
- Pay down existing credit card balances to reduce your credit utilization ratio.
- Make all your payments—credit cards, loans, utilities—on time.
- Limit new credit inquiries leading up to your mortgage application.
Even a slight improvement in your credit score could help you secure a better interest rate and save thousands over the life of your loan.
2. Shop Around for the Best Rates
Did you know that mortgage rates can vary significantly between lenders? It pays—literally—to shop around and compare offers from multiple lenders. At Aron Home Loans, we specialize in finding the best rates across Arizona, California, New Mexico, and Texas, giving you a selection of options tailored to your needs.
When comparing lenders, be sure to look beyond just the interest rate. Examine the annual percentage rate (APR), lender fees, and closing costs to get a full picture of what each loan will truly cost you.
3. Choose a Loan Type That Fits Your Budget
In addition to shopping for the best rates, consider exploring different loan types. While a 30-year fixed-rate mortgage is the most common choice, it’s not the only option:
- Adjustable-Rate Mortgages (ARMs): These loans have a lower initial rate that’s locked for a few years (e.g., 5, 7, or 10 years) before adjusting annually. If you plan to move or refinance before the fixed period ends, an ARM could save you money.
- 15-Year Loans: These have higher monthly payments but lower interest rates and allow you to pay off your loan quicker, saving money on interest over time.
Having flexibility in choosing the right loan can help make homeownership more affordable in the long run.
4. Make a Larger Down Payment
Saving for a larger down payment may seem challenging, but it can have a dramatic impact on your loan terms and monthly payments. By putting down 20% or more, you can eliminate the need for private mortgage insurance (PMI) and reduce your loan amount, resulting in a lower monthly cost.
Even if 20% isn’t feasible, increasing your down payment beyond the minimum requirement can still improve your overall financial position.
5. Focus on Your Budget
Rising interest rates mean you may need to rethink your budget. Take a holistic look at your finances, including your monthly income and expenses. Use the 28/36 rule as a guideline: Your monthly mortgage payment, including taxes and insurance, should not exceed 28% of your gross monthly income, while your total debt payments should stay under 36%.
Being mindful of your budget ensures that you’re not taking on more house than you can afford in a higher-rate environment.
6. Look for Down Payment Assistance Programs
Many states, including Arizona, California, New Mexico, and Texas, offer assistance programs specifically designed for first-time homebuyers. These programs often provide grants, low-interest loans, or tax credits to help make homeownership more affordable. Research your state’s options or ask Aron Home Loans about programs you may qualify for in your area.
7. Consider Rate Locking
If you’re concerned about rates rising even further, ask your lender about a rate lock. A rate lock allows you to secure your interest rate for a specific period (typically 30, 60, or 90 days) while you finalize your home purchase. This can protect you from market volatility and ensure your loan terms remain predictable.
Conclusion
Rising mortgage rates don’t mean you have to put your dreams of homeownership on hold. By taking proactive steps like improving your credit, shopping around for the best deal, and exploring innovative loan options, you can find solutions that fit your financial situation.
At Aron Home Loans, we’re here to guide first-time buyers in Arizona, California, New Mexico, and Texas through every step of the mortgage process. Contact us today to start your home-buying journey, even in today’s challenging market.